Buying your first home in Southern California can feel out of reach, especially when you start doing the math on a down payment. The good news: there is real money on the table for first-time buyers in San Diego and Riverside County. Between city, county, and state programs, qualified buyers can get help covering a big share of their down payment, and some of that help never has to be paid back.
Below, our team at HOMEBASE Real Estate breaks down the major first-time homebuyer programs available in 2026, who they are for, and how to get started.
First, What Counts as a "First-Time Homebuyer"?
You might qualify even if you have owned a home before. Most assistance programs define a first-time buyer as someone who has not owned a home in the past three years. Each program sets its own rules, so always confirm with a participating lender, but don't count yourself out too early.
Most programs also share a few common requirements:
- Income limits based on your household size and the Area Median Income (AMI) for the county
- A maximum purchase price for the home
- A homebuyer education course completed before closing
- Owner-occupancy, meaning the home must be your primary residence
- A participating lender who processes the assistance alongside your first mortgage
San Diego County Programs
The San Diego Housing Commission (SDHC) administers several first-time homebuyer programs for the City of San Diego, the County of San Diego, and the City of Chula Vista. Here is how they compare.
SDHC programs can help cover a big share of the down payment on your first San Diego home.
City of San Diego: Low-Income Program (under 80% AMI)
- Deferred-payment loan of up to 17% of the purchase price (max $125,000) at 3% simple interest
- Plus a grant of 4% of the purchase price, up to $10,000, that is forgiven
- No monthly payments for 30 years as long as you live in the home; the loan is due when you sell or move out
- Maximum purchase price: $883,025
City of San Diego: Middle-Income Program (80% to 150% AMI)
- $50,000 in total assistance: a $40,000 deferred loan plus a $10,000 grant
- 4% simple interest, with payments deferred for five years, then repaid over 10 years
- Maximum purchase price: $1,250,000
This is one of the few programs in the region built for middle-income buyers, which makes it a great fit for many working professionals who earn too much for traditional assistance but still struggle with San Diego prices.
County of San Diego
- Low-income (under 80% AMI): loan of up to 22% of the purchase price for down payment and closing costs, at 3% simple interest with a 30-year deferral
- Moderate-income (80% to 120% AMI): loan of up to 17% of the purchase price, at 3% simple interest
- Maximum purchase price: $743,000 (effective June 1, 2026)
- Available in participating cities and the unincorporated county
City of Chula Vista
- Loan of up to 22% of the purchase price, up to $120,000, at 3% simple interest with a 30-year deferral
- Maximum purchase price: $807,500
For all SDHC programs, buyers need a fixed-rate first mortgage, a minimum down payment of their own (generally at least 3%), and an SDHC-approved homebuyer education course.
Riverside County Programs
Riverside County Housing & Workforce Solutions runs two first-time homebuyer programs: the HOME FTHB Program (for households earning up to 80% of AMI) and the PLHA FTHB Program (up to 120% of AMI).
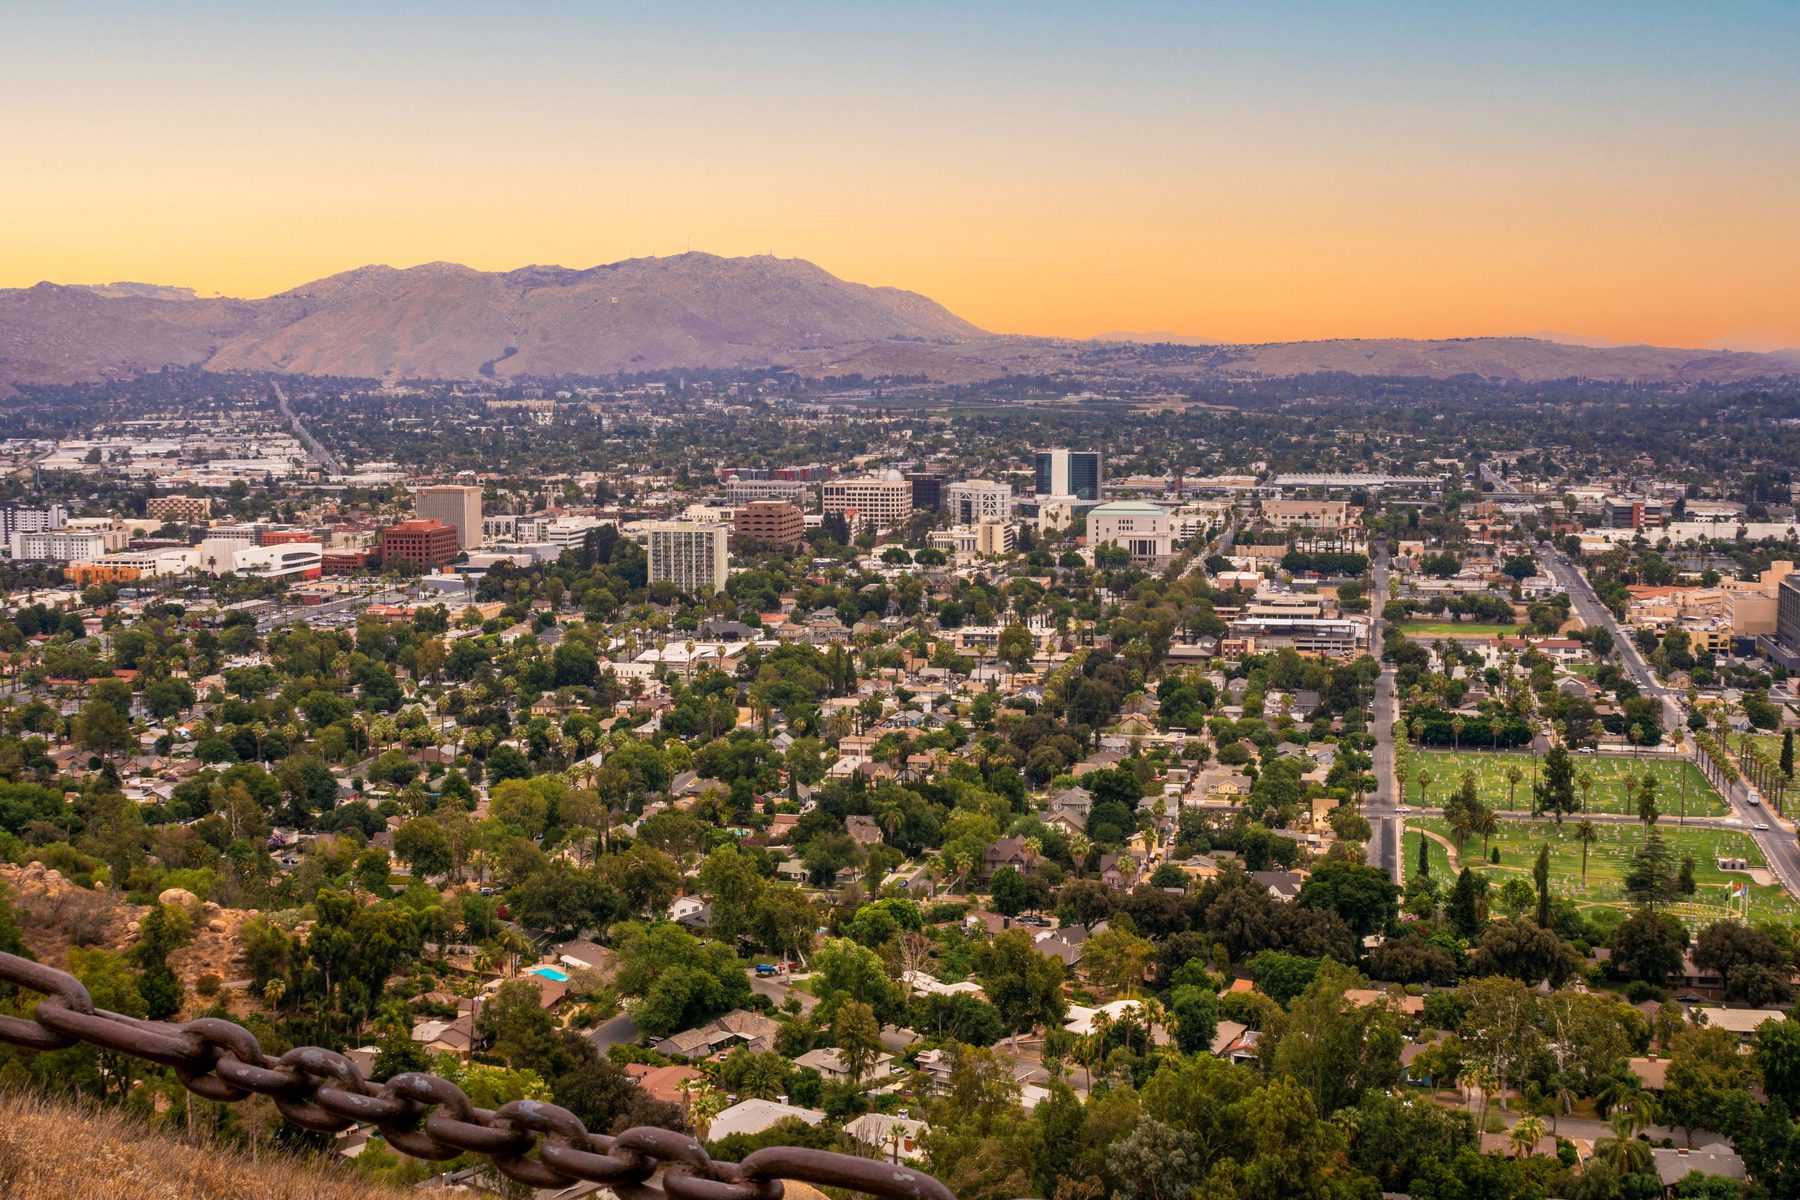
Riverside and the surrounding Inland Empire, seen from Mount Rubidoux.
How the Assistance Works
- Up to 20% of the sales price, limited to the amount you actually need
- No monthly payments. The assistance is a second loan that is only due if you sell or do a cash-out refinance
- It becomes a grant after 15 years. Stay in the home for the 15-year affordability period and you never pay it back
- Closing cost assistance is not currently available under these funding sources
2026 Income Limits (effective July 1, 2026)
| Household Size | HOME (80% AMI) | PLHA (120% AMI) |
|---|---|---|
| 1 | $68,900 | $89,520 |
| 2 | $78,750 | $102,240 |
| 3 | $88,600 | $114,960 |
| 4 | $98,400 | $127,800 |
| 5 | $106,300 | $138,000 |
| 6 | $114,150 | $148,200 |
Maximum Purchase Prices
- Single-family home: $607,050
- Condo or townhouse: $470,250
- Manufactured home: $201,400
Where You Can Buy
These programs cover unincorporated Riverside County and cooperating cities, but some cities are not included. For example, the HOME program excludes Riverside, Corona, Temecula, Murrieta, Menifee, Moreno Valley, Lake Elsinore, and several Coachella Valley cities, while the PLHA program excludes a shorter list that includes Riverside, Corona, Menifee, and Perris. Check the county's current list before you start your home search.
Buyers must also complete an 8-hour homebuyer education class after a participating lender confirms eligibility.
Statewide Programs Through CalHFA
No matter which county you buy in, the California Housing Finance Agency (CalHFA) offers programs that can be used on their own or, in some cases, stacked with local assistance.
MyHome Assistance Program
A deferred-payment junior loan for down payment and closing costs: up to 3.5% of the purchase price with an FHA loan, or up to 3% with a conventional loan. There are no monthly payments; you repay it when you sell, refinance, or pay off your first mortgage.
California Dream For All
Dream For All is a shared appreciation loan for first-generation homebuyers, offering up to 20% of the purchase price (max $150,000) toward your down payment or closing costs. Instead of interest, you repay the original amount plus a share of the home's appreciation when you sell or refinance: 20% of the appreciation for most borrowers, or 15% for households at or below 80% AMI.
Recipients are chosen by a randomized drawing. The most recent application portal closed on March 16, 2026, so if you're interested, watch for the next round and have your pre-approval ready.
CalPLUS and ZIP
CalPLUS loans pair a fixed-rate first mortgage with extra help, such as the Zero Interest Program (ZIP) for closing costs. These can be helpful for buyers who have their down payment covered but need a hand with closing costs.
Tips for Making the Most of These Programs
- Start with a participating lender. Every program on this list runs through approved lenders, and they will screen you for the programs you qualify for.
- Take your homebuyer education course early. It is required almost everywhere, and finishing it early keeps you from delaying your closing.
- Know your price ceiling before you shop. Maximum purchase prices vary a lot between programs, so it pays to know your limits before you fall in love with a home.
- Ask about stacking. In some cases, local assistance can be combined with CalHFA programs. Your lender can tell you which combinations are allowed.
- Be ready to move quickly. Funding is limited and some programs open and close throughout the year.
- Work with an agent who knows the programs. Assistance programs can add steps and time to escrow, and sellers need to know your offer is solid.
Ready to Buy Your First Home?
Homeownership in San Diego and Riverside County is more achievable than many buyers think. Whether you're eyeing a condo in Chula Vista or a single-family home in the Inland Empire, the HOMEBASE Real Estate team can connect you with trusted lenders, help you figure out which programs fit your situation, and guide you from pre-approval to closing.
Reach out to our team today to start your homebuying journey.
Program details, income limits, and purchase price limits are current as of September 2026 and can change at any time. Always confirm current guidelines with the program administrator or a participating lender.
Sources
Check out this article next